Order mechanicsYou sets it · reducible: Yes
Order Types: What Each Promises, What Each Costs
This is the only trading cost nobody else decides for you. It is also the one most people choose by default.
Key takeaways
- Every order type is a position on one trade-off: certainty of execution versus certainty of price. You cannot have both.
- A market order guarantees you trade. It guarantees nothing about the price.
- A limit order guarantees the price will not be worse than you named. It guarantees nothing about trading at all.
- The failure modes are opposite: a market order fails by costing more, a limit order fails by leaving you out.
In this article · 8 sections
The short answer
Every order type is a position on one trade-off: certainty of execution against certainty of price. A market order guarantees you trade and guarantees nothing about the price. A limit order guarantees the price and guarantees nothing about trading. This is the one cost input nobody else decides for you.
Of everything this publication covers, the order type is the only component that nobody else decides. The broker sets the spread. The market sets the depth. You set this — and it is routinely chosen by whichever button is largest.
Every order type is a position on a single trade-off, and understanding that one sentence is most of the subject:
You can have certainty of execution, or certainty of price. You cannot have both.
Everything below is a way of choosing where to sit on that line.
Market orders
A market order says: trade now, at whatever price is available.
It guarantees that you will trade, assuming the market is open and there is anything on the other side.
It guarantees nothing about price. You get what exists when the order arrives, which may be better or worse than what you saw. In a deep, calm market the difference is usually small. Around a release or in a thin hour it is not.
A market order is the right instrument when being in or out matters more than the exact level — closing a position you have decided to be rid of, for instance. It is the wrong instrument when a few units of price would change whether the trade made sense, which is more often than people assume.
Limit orders
A limit order names a price and says: trade at this or better, and not at all otherwise.
It guarantees that you will not be filled worse than your price.
It guarantees nothing about being filled. Price may approach your level, turn, and leave without you. It may touch your level and still not fill, because being at a price is not the same as there being someone there to trade with at that price when your order is in the queue.
A limit order's failure is invisible and therefore underrated. A market order that fills badly leaves evidence. A limit order that never fills leaves nothing at all — and if the trade would have worked, that absence cost you more than any spread.
Stop orders
A stop order is an instruction that becomes active when price reaches a level. Until then it does nothing.
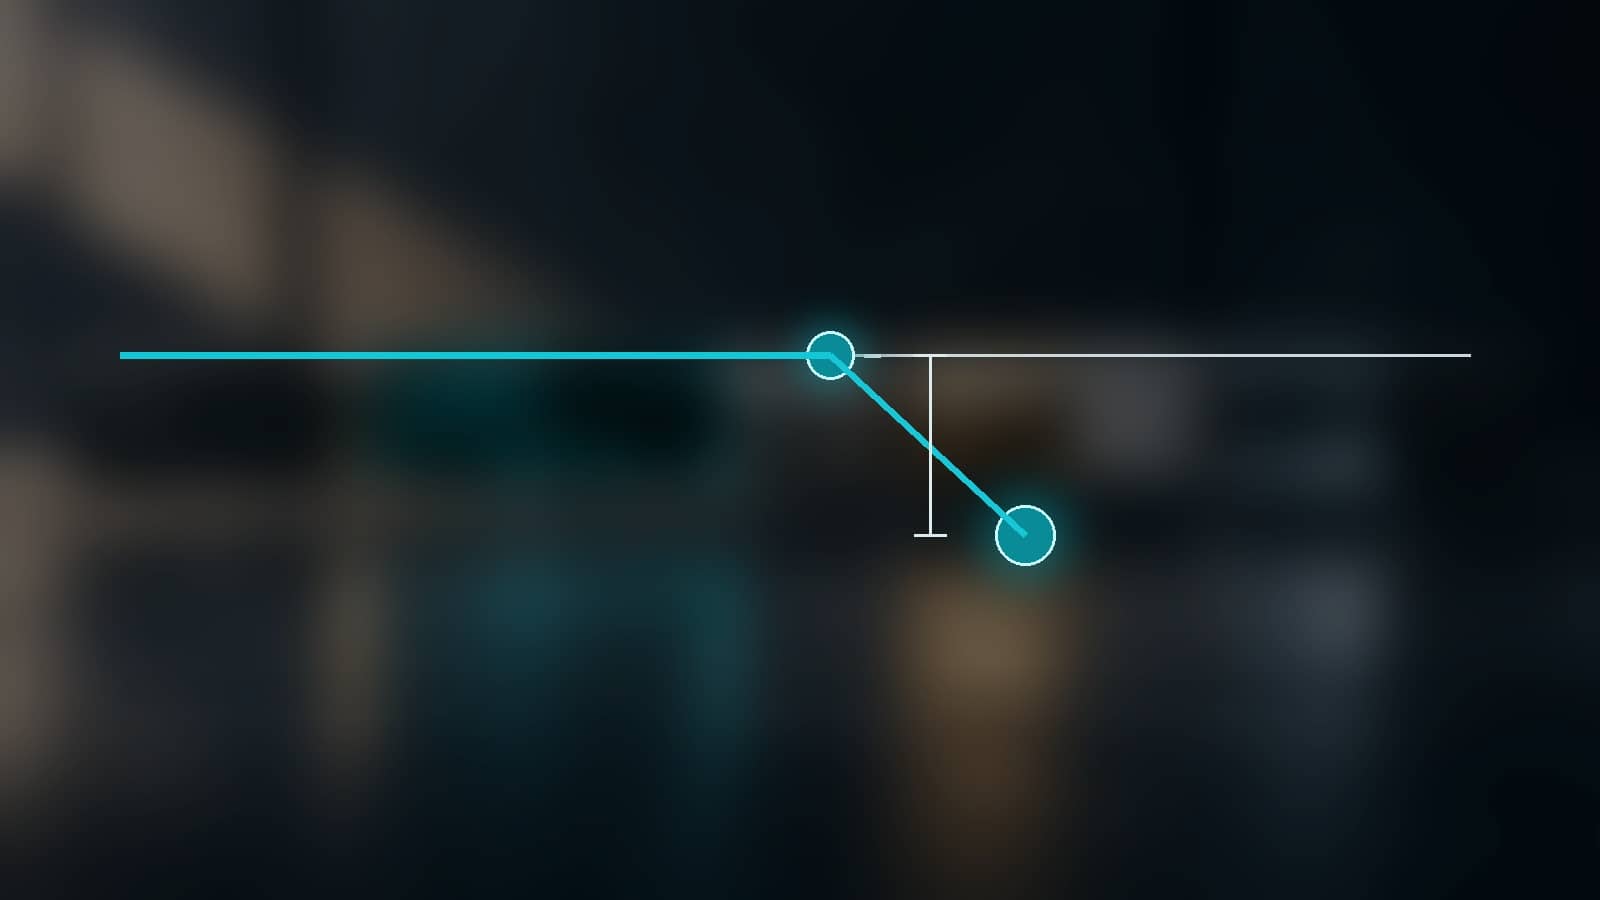
The critical detail: a standard stop becomes a market order once triggered. It carries all of a market order's properties — including no guarantee of price. The level is the trigger, not the fill. This is important enough that it has its own article.
A stop-limit becomes a limit order instead, which caps the price you will accept. That solves the price problem and introduces the limit order's problem: if price moves straight through your limit, you are not filled, and you are still in a position you wanted to leave. For an exit this is a meaningful risk, and it is the reason stop-limits are more common for entries than for protective exits.
Choosing
The honest framing is not "which is best" but "which failure can I live with".
Use a market order when not trading is the worse outcome: exits you have decided on, positions you need closed, anything where being out matters more than the price of getting out.
Use a limit order when a worse price would change the logic of the trade: entries at a level you chose for a reason, anything where missing it is an acceptable outcome.
Use a stop when you want an exit to happen without you watching, and accept that the fill may be past the level.
The mistake to avoid is using one type for everything, because then the failure mode is the same every time and it compounds.
What "best execution" does and does not cover
There is a regulatory obligation here, and knowing its shape stops you expecting the wrong thing from it.
Under MiFID II, firms must take all sufficient steps to obtain the best possible result for clients, weighing price, costs, speed, likelihood of execution and settlement, size, nature and other relevant considerations. For retail clients the result is assessed on total consideration — price together with the costs associated with execution.
And, decisively for this page: where a client gives a specific instruction, the firm must follow it.
A market order is a specific instruction. It says now. A firm that executes it faithfully may hand you a worse price than you hoped for and will have discharged its duty exactly. The obligation is about the firm's process and the result taken as a whole; it is not a safety net under a choice you made.
Which brings the subject back where it started. The order type is the one cost you control, and the regulation is explicit that choosing it is yours to do.
Deciding before, not during
The practical difficulty is that order type is chosen at the moment of acting, which is the worst moment to be weighing trade-offs. The way round it is to decide the terms before the position exists — what price would make this trade not worth doing, and therefore whether a fill beyond it is acceptable.
That is a planning habit rather than a trading technique, and it is the one thing on this page that does not depend on your broker at all.
Where this sits
Order choice is the most controllable of the components of trading cost. Its direct consequence is slippage, and the special case that catches people out is the stop order.
Sources and references
- Article 27 — Obligation to execute orders on terms most favourable to the client (MiFID II) — European Securities and Markets AuthorityRegulator · retrieved 8 October 2026